The real lost about 8% against the dollar on Monday after Lula’s re-election, Brazil’s central bank data show, a move that reaches Argentina’s trade, bonds and Mercosur plans.
Brazil is Argentina’s largest trading partner, so the outcome matters to exporters, to investors in Argentine bonds and to President Milei’s push to loosen Mercosur, the South American trade bloc. Lula, who won by about 4.4 million votes according to Brazil’s electoral court, begins his new term on Jan. 5, 2027.
What the markets repriced
Investors had bet on Lula’s rival, Flávio Bolsonaro, whom Milei backed. After the Oct. 4 first round the real strengthened and Argentina’s country risk, the extra yield investors demand on its bonds over US Treasuries, fell below 600. Monday more than reversed both: the real lost about 8% and country risk reached 765 points, the highest since October 2025, according to Brazil’s central bank and JP Morgan’s index.
Our calculation from the two central banks’ daily reference rates shows how far the move went. A real now buys about 4% fewer pesos than before the first round, so Brazilian goods cost less in pesos than they did on Oct. 2.
Trade
Argentina’s deficit with Brazil fell to US$2.2 billion in January-September from US$5.1 billion a year earlier, INDEC, the national statistics agency, reported. Abeceb, a consultancy, has attributed the drop mainly to weak Argentine demand for imports.
Brazil took US$9.8 billion of Argentine exports in that period, and cars are among the most exposed: more than 63% of Argentina’s auto exports went to Brazil in January-September, the carmakers’ association ADEFA said.
A weaker real cuts both ways for that trade. It makes Brazilian goods cheaper against Argentine ones, which could revive imports that have fallen this year, and it makes Argentine exports more expensive for Brazilian buyers. If the real recovers as Lula shows how he will handle the budget, the effect fades. If it stays weak, Argentine industry competes at a disadvantage. Abeceb’s Gustavo Pérego told La Nación that car exports depend even more on Brazil’s economic activity than on the exchange rate.
Brazil’s budget
The market’s worry is the budget. Brazil’s gross government debt was 82.9% of GDP in August, according to its central bank, and its benchmark interest rate, cut several times this year, is 13.75%. Economists put the total deficit near 9% of GDP once interest payments are counted.
Lula’s team targets a budget surplus before interest payments of about 1.3% of GDP by 2030. Whom he names as finance minister, and how he deals with a Congress where Bolsonaro’s allies hold sway, will set the tone. A calmer Brazil would ease the pressure on Argentine bonds, which moved with the real after both rounds, and a weaker real and higher Brazilian yields would add to it.
Mercosur and diplomacy
The EU-Mercosur interim trade agreement has applied provisionally since May 1, the European Commission says, so the election does not decide it. Where the result does matter is Milei’s wish to let Mercosur members cut tariffs and sign trade deals with outside partners, which needs agreement among members. Our Oct. 7 analysis reported that the government saw a Bolsonaro win as the opening for that, and economist Fausto Spotorno told La Nación he expects the effort to stall unless Lula changes his position.
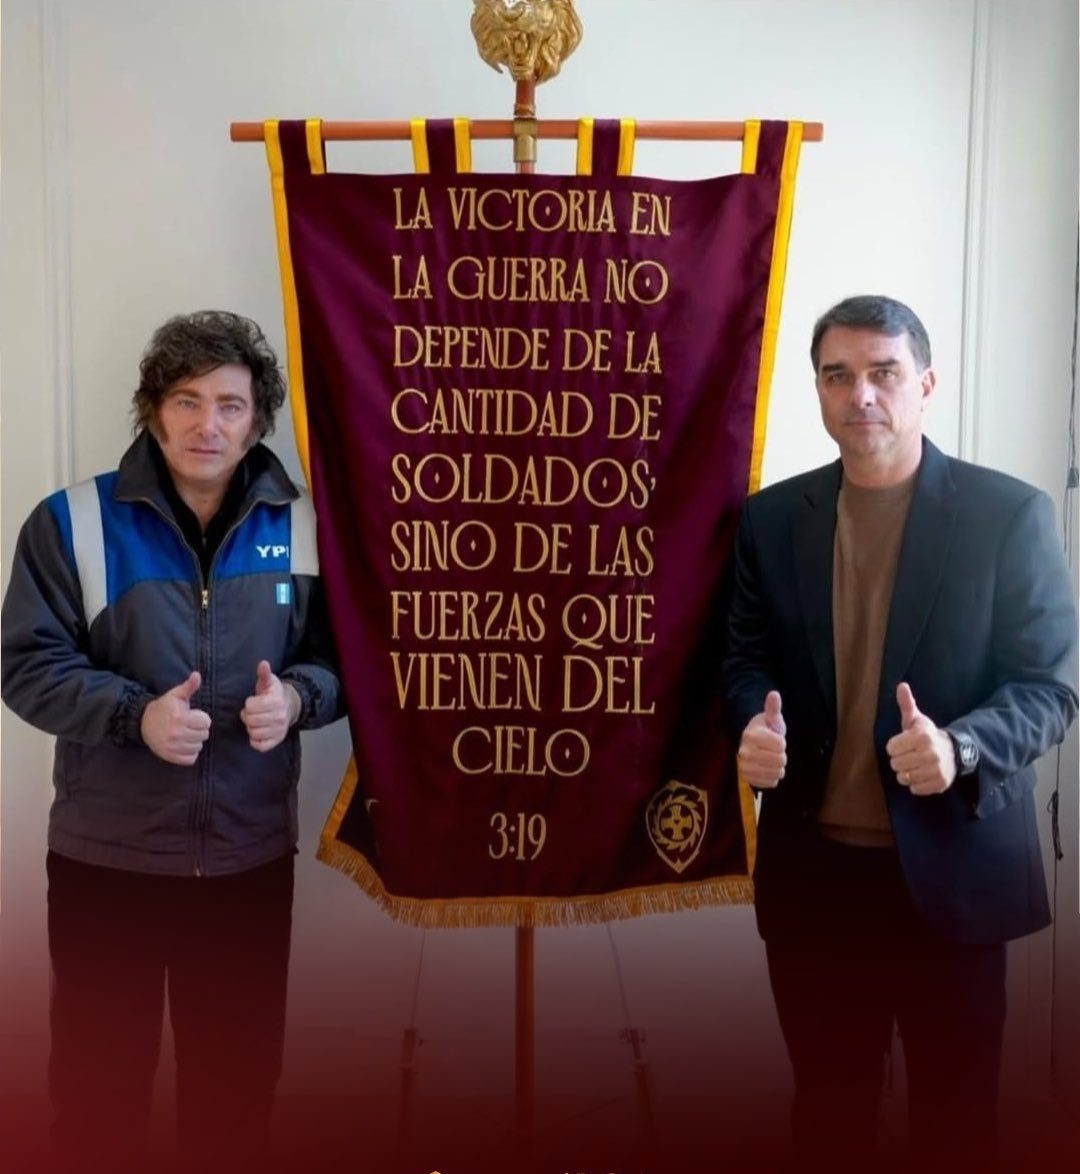
Milei, who called Lula a thief in July, had not congratulated him by Monday afternoon, and Brazil had already accused him of meddling in its election. An Argentine government source told La Nación that technical work on trade continues regardless.
The dates to watch are the US Federal Reserve’s interest-rate decision on Wednesday, the Mercosur presidents’ summit in Montevideo in December, where Milei and Lula could meet, and Lula’s swearing-in on Jan. 5.